The Strategic Pivot to Domestic Autonomy
The U.S. Department of Energy (DOE) has officially launched a ambitious new blueprint aimed at securing a robust, domestic battery supply chain by 2030. While previous federal initiatives centered heavily on clean energy transition and social equity, this latest strategy reflects a shift in priority toward national security, grid stability, and the massive energy requirements of emerging technologies like AI data centers. By localizing everything from raw mineral extraction to the production of complex battery subcomponents, the U.S. aims to decouple its critical infrastructure from an heavy reliance on international markets, particularly China.
The scale of this challenge is significant, with current estimates suggesting a four-fold increase in domestic battery demand between 2025 and 2035—growing from 179 gigawatt-hours to a staggering 707 GWh. To meet this surge, the DOE has outlined a three-tiered approach that addresses the entire lifecycle of battery technology. This shift is critical, as recent years have seen a cooling in the industrial sector, with billions of dollars in planned battery projects being canceled or downsized. This new policy serves as a foundational attempt to reignite domestic investment in a sector that is increasingly viewed as the backbone of modern energy infrastructure.
The DOE’s Three-Step Strategy
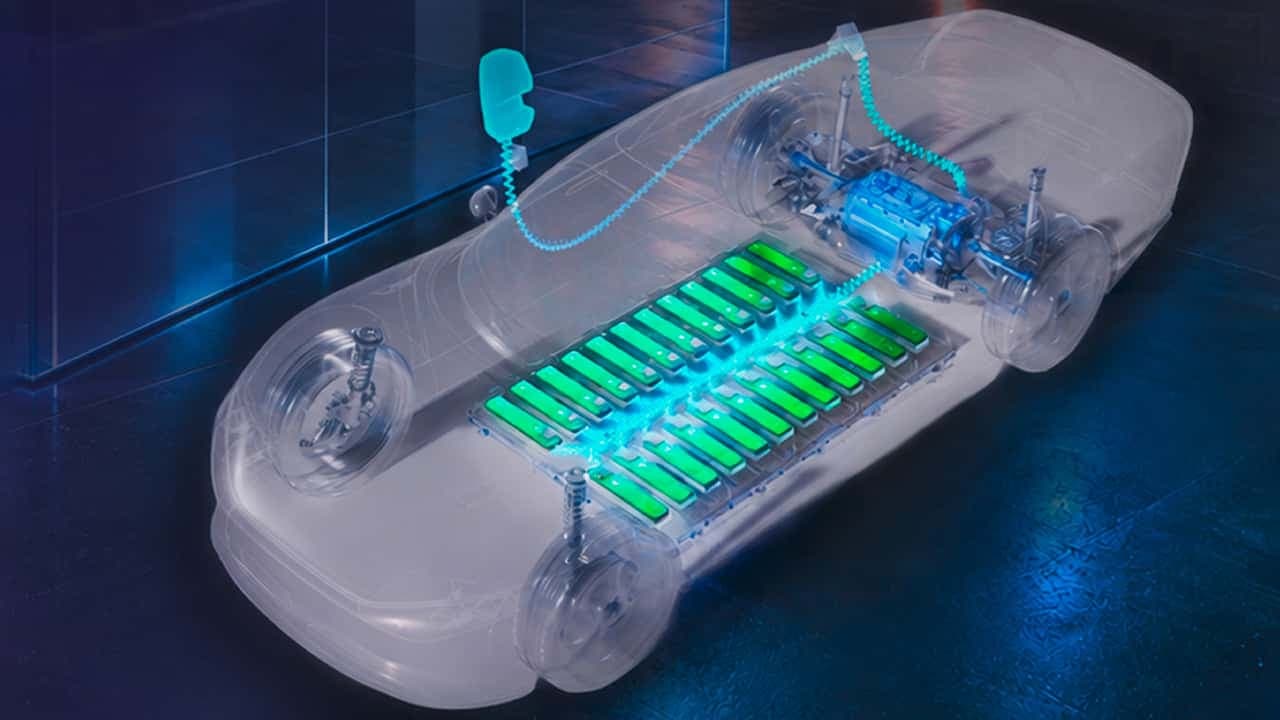
- Mine-to-Market Integration: The primary objective is to move away from a fragmented, import-dependent supply chain toward an integrated system. By prioritizing domestic extraction, refining, and the production of anodes, cathodes, and electrolytes, the government plans to create a continuous value chain that functions entirely within U.S. borders by 2030.
- Discovery-to-Deployment: This phase targets manufacturing leadership by 2035. The goal is to bridge the notorious "valley of death" that often prevents promising laboratory research from reaching commercial viability. This involves targeted investments in companies specializing in next-generation battery architectures, such as solid-state cells, which offer superior density and safety profiles.
- Reliable Storage Applications: Beyond transportation, the focus has broadened to include utility-scale storage. By fostering advancements in battery durability and cost-efficiency, the strategy ensures that the power grid can handle the extreme loads generated by AI, robotics, and consumer electronics, ensuring stability for both private and public sectors.
Why it Matters: The Economic Reality
The urgency behind this roadmap is fueled by sobering industry data. According to reports from the think tank E2, the U.S. industrial landscape suffered significant setbacks between 2022 and 2026, with over $42 billion in battery-related projects being canceled or delayed. This contraction resulted in the loss of more than 85,000 potential jobs. When viewing the clean energy sector at large, those numbers balloon to $137 billion in lost investment and 240,000 jobs. The DOE’s new plan is designed to be a stabilizing force in this volatile environment.
By reframing battery development as a matter of national security and AI readiness, the government is attempting to move the narrative beyond the typical EV vs. combustion debate. Even as the automotive market experiences cyclical fluctuations, the demand for stationary storage and energy-dense, reliable battery chemistry is poised for exponential growth. Automakers and tech firms alike will be keeping a close watch on how these federal investments prioritize companies capable of bringing high-performance battery technology to market at scale, effectively turning laboratory breakthroughs into the power cells that will run everything from the electric vehicles of tomorrow to the data centers driving the AI revolution.