The 2% Reality Check
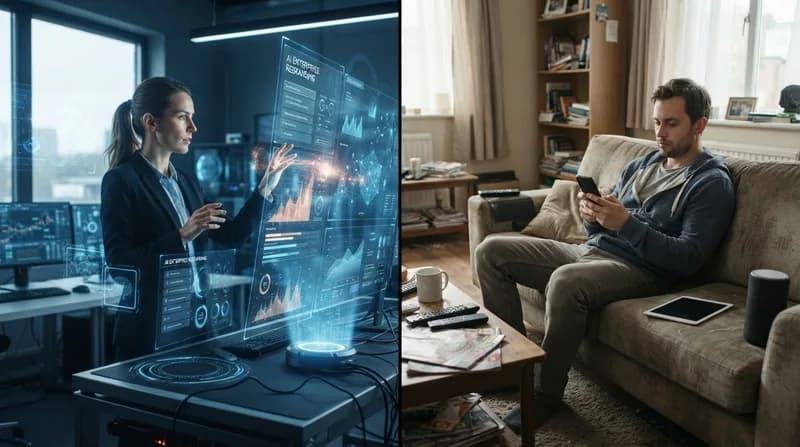
The artificial intelligence industry is currently navigating a strange paradox. While major tech executives—including leaders from Meta, OpenAI, and Anthropic—gather with high-ranking government officials to sign "morally binding" safety pledges, the actual impact on the average consumer’s wallet remains remarkably slim. Recent industry data suggests that despite the massive rebranding efforts, such as the executive push to categorize advanced models as "super intelligence," only 2% of the general consumer population is actively investing in or adopting these tools.
This divide highlights a glaring reality: the bulk of AI’s current financial momentum is rooted strictly in enterprise applications. While companies are spending billions to integrate these systems into their infrastructure, individuals remain hesitant. The industry is responding by putting a friendlier face on its products, yet the "ugly economics" of consumer AI—the difficulty of proving tangible daily value versus the subscription costs—continues to be the primary friction point for widespread adoption.
The Shifting Landscape of AI Finance
Public markets have become notably more discerning, causing ripples throughout the startup ecosystem. High-profile companies are retreating from initial public offerings, with firms like Oura pulling back from the IPO market entirely. Similarly, heavyweights like OpenAI are pivoting back toward private funding structures, and Anthropic’s leaked financial documents suggest that public investors are demanding more than just vision; they are demanding proven, scalable revenue models that current consumer AI products have yet to reliably demonstrate.
However, investment in specialized B2B (business-to-business) sectors continues to thrive where AI solves concrete, real-world operational inefficiencies. A prime example is the logistics and supply chain sector, where firms like Quartermaster have successfully raised $140 million to bring real-time sensor intelligence to the maritime shipping industry—a space largely untouched by modern automation until now. Furthermore, Atomic, a supply-chain startup founded by former Tesla engineers, has demonstrated that AI-driven efficiency is not just theoretical; they are already managing 90% of procurement for a major player like DoorDash.
Why it Matters
- Enterprise vs. Consumer: The vast disparity between the 2% consumer adoption rate and massive enterprise spending shows that AI is currently a backend industrial tool rather than a mass-market lifestyle device.
- Capital Discipline: The move away from public markets toward private funding indicates that the "AI gold rush" era is evolving into a more traditional, margin-focused business cycle.
- Sector-Specific Success: Startups targeting legacy industries—like maritime shipping, satellite insurance, and advanced logistics—are finding far more traction than those attempting to build general-purpose consumer agents.
Outlook: Beyond the Hype
Looking ahead, the industry is entering a phase of consolidation and structural shifts. Startups that can solve niche, high-cost problems in heavy industry are flourishing, while those relying on broad, consumer-facing "super intelligence" are struggling to justify their valuations. As the government continues to refine the regulatory framework around these tools, companies will likely focus their energy on proving utility in operational environments where ROI is measurable and immediate, rather than chasing the elusive, price-sensitive individual consumer.